ATTORNEY COLLABORATION
Connecting Estate Planning With Smarter Mortgages
Bridging legal counsel and mortgage advisory to protect family wealth, optimize trust liquidity, and streamline real estate transfers with fiduciary precision.
Direct attorney collaboration · Specialized trust & probate financing structures
MORTGAGE & ESTATE ADVISORY
The Hidden Complexity of
Real Estate Debt
While estate plans seamlessly convey legal title to real property, they rarely resolve the contractual encumbrances tied to the underlying debt. A deed transfer alone cannot amend promissory note liabilities, leaving beneficiaries and trust entities vulnerable to unintended acceleration clauses, conflicting lien priorities, and institutional underwriting roadblocks.
Navigating statutory protections under the Garn-St Germain Act, establishing non-borrower successor qualifications, and structuring title changes without impairing lender covenants requires specialized mortgage analysis. Proactive debt alignment ensures that meticulously drafted testamentary directives are not compromised by secondary market servicing mandates.
CRITICAL PRACTICE ADVISORY
Fannie Mae, Freddie Mac, and private portfolio servicers enforce strict, non-negotiable guidelines for trust-held properties. Coordinating financing mechanics prior to deed recordation prevents unexpected calls and protects client assets.
COLLABORATIVE PRACTICE AREAS
Strategic Mortgage Intersections For
Attorneys
Detailed underwriting clarity and structured advisory support across probate, estate planning, and asset division matters.
1. Inheritance & Encumbered Real Estate
Evaluating encumbered real property passing to heirs during probate. We assess existing promissory notes, resolve co-heir equity allocation, and ensure compliance with Garn-St. Germain statutory transfer rights.
- Garn-St. Germain exemption verification
- Successor-in-interest documentation review
- Co-heir buyout and distribution analysis
2. Mortgage Assumptions & Due-on-Sale
Clarifying loan assumability across conventional, FHA, and VA debt instruments. We examine lender underwriting criteria, release of estate liability, and statutory transfer exceptions to avoid unintentional loan acceleration.
- Due-on-sale covenant risk assessment
- FHA and VA qualified assumption audits
- Formal liability release petition guidance
3. Refinancing & Equalization Buyouts
Structuring specialized cash-out and rate-and-term transactions to facilitate clean co-beneficiary buyouts or marital dissolution property divisions while removing departed parties from existing mortgage liability.
- Owelty lien structuring and cash allocations
- Sole-debtor qualification pathways
- Title release and deed transfer coordination
4. Trust Vesting & Underwriting Alignment
Resolving lender underwriting friction when vesting encumbered real property into revocable living trusts or irrevocable estate vehicles. We ensure agency compliance without disturbing low existing interest rates.
- Fannie Mae certificate of trust alignment
- Trustee signature block verification
- Title continuity without alienation triggers
5. Property Equity & Estate Liquidity
Unlocking non-liquid real estate equity to fund estate tax liabilities, long-term fiduciary care obligations, or equalization distributions without mandating distressed fire-sales of legacy family assets.
- Non-recourse liquidity strategies for trusts
- Asset-based and DSCR bridge financing
- Estate tax obligation settlement vehicles
6. Strategic Intergenerational Purchases
Structuring cross-generational transactions, including Family Opportunity Mortgages for aging parents or adult disabled dependents, and complex fiduciary property acquisitions requiring court approval.
- Family Opportunity Mortgage qualification
- Fiduciary borrower documentation standards
- Cross-collateralized acquisition models
PROFESSIONAL SYNERGY
Seamless Integration With
Your Practice
Estate planning and mortgage financing must work in synchrony to protect client assets. We coordinate directly with legal counsel to ensure property vesting, deed language, and liquidity strategies honor the exact terms of every trust declaration without delay.
Direct attorney concierge · File reviews completed within 24 hours
Analyzing Deed & Vesting Structures
Thorough audit of title deeds, beneficiary designations, and spousal rights to verify property titling accurately reflects current trust parameters and avoids unintended probate triggers.
Title & Vesting VerificationCoordinating Trust-Aligned Financing
Structuring custom loan architecture tailored for revocable, irrevocable, or testamentary trusts: preserving estate asset liquidity while strictly honoring fiduciary compliance obligations.
Fiduciary Financing StructureExecuting Clear Communication
Delivering synchronized closing milestones and document previews directly to counsel, ensuring real-time visibility, fast file turnarounds, and zero friction at recording.
Synchronized Legal CoordinationPROFESSIONAL PROFILE & CREDENTIALS
Collaborative Expertise You Can
Trust
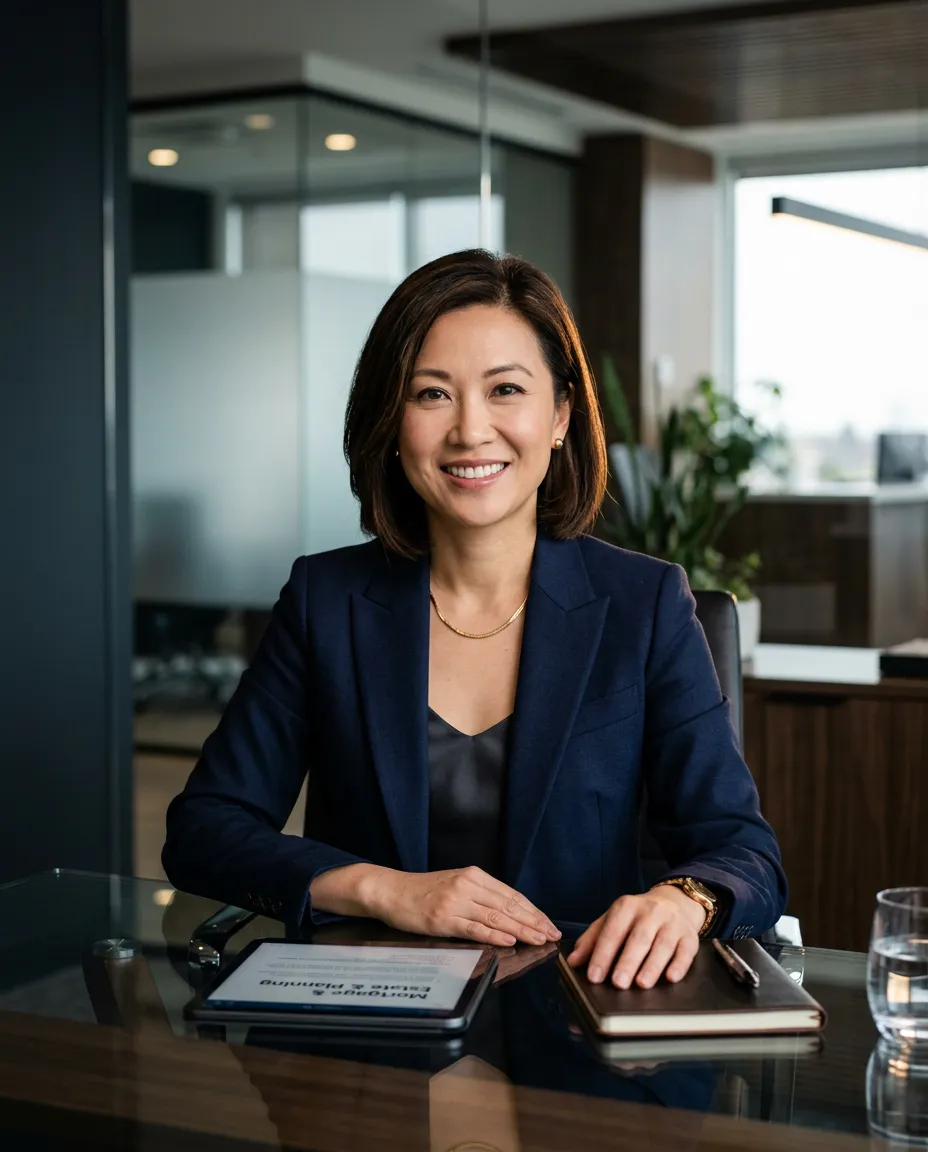
Dianna Michele Thompson
Mortgage Advisory & Estate Planning Liaison
Providing specialized financial analysis for legal professionals handling estate settlements, trusts, and real property transitions across jurisdictions.
Estate planning attorneys and fiduciary litigators operate in an exacting environment where timing, accuracy, and clear division of responsibility are paramount. Dianna’s advisory framework is built around supporting legal strategies with institutional-grade mortgage analysis - never providing legal counsel, but ensuring debt structures align seamlessly with testamentary objectives.
Technical Mortgage Competency & Credentials
Backed by extensive experience across conventional, jumbo, trust-vested, and non-delegated lending programs. Dianna is deeply versed in the Garn-St Germain Act, successor-in-interest qualifications, and underwriting guidelines governing real property held in revocable and irrevocable trusts.
Direct Co-Counsel & Law Firm Alignment
Practicing attorneys require responsiveness, discretion, and documented clarity. Dianna communicates directly with paralegals, trust administrators, and estate counsel to provide liquidity evaluations, refinancing analyses for equalizing beneficiary inheritances, and title vesting coordination.
Strict Scope Discipline & Boundary Integrity
Trust is preserved by respecting professional boundaries. Dianna operates strictly within mortgage lending and financial analysis parameters, deliberately deferring all tax, probate, and legal questions back to retained counsel. Your client relationship remains fully insulated and protected.
STATUTORY & REGULATORY PROTOCOLS
Technical Mortgage Clarifications For
Estates
Authoritative guidance on federal lending statutes, successor protections under CFPB servicing rules, and structured mortgage solutions for probate and trust estates.
Does transferring inherited residential property trigger the lender's due-on-sale clause under federal law?
Under the Garn-St. Germain Depository Institutions Act of 1982 (12 U.S.C. § 1701j-3), mortgage lenders are federally prohibited from exercising due-on-sale acceleration clauses upon transfers resulting from the death of a borrower to a relative, or transfers where a surviving spouse or child assumes occupancy. The loan remains valid and intact under its existing rates and terms.
What rights and protections do heirs receive under CFPB mortgage servicing rules?
Pursuant to Consumer Financial Protection Bureau (CFPB) Regulation X (12 CFR § 1024.30), once an heir or beneficiary verifies their legal identity and ownership interest in the real property, loan servicers must recognize them as a confirmed successor-in-interest. This status grants full account access, statement disclosures, escrow records, and loss mitigation review rights without requiring immediate personal liability on the debt.
Can real property held in a revocable or irrevocable trust obtain mortgage financing?
Yes. Real estate titled within revocable living trusts is broadly eligible for conventional agency financing through Fannie Mae and Freddie Mac guidelines, provided the trust documentation meets standard settler and trustee qualification standards. Irrevocable trusts require specialized portfolio residential lending or estate-level bridge financing structured specifically to adhere to the trust indenture.
How can one heir obtain financing to buy out co-heirs without triggering tax re-assessments?
When multiple beneficiaries inherit real estate and one successor wishes to retain the home, a structured fiduciary mortgage or estate equalization loan can be executed directly to the probate estate or trust entity. This provides non-retaining beneficiaries their cash share while preserving applicable parent-to-child or intergenerational property tax exclusion privileges.
Does a confirmed successor-in-interest become personally liable for the inherited mortgage debt?
No. Establishing legal status as a confirmed successor-in-interest allows an heir to maintain regular loan payments, communicate with servicers, and avoid foreclosure without obligating their personal credit or personal assets. Personal liability is only established if the heir voluntarily elects to execute a formal assumption agreement or completes an independent refinance.
MANDATORY STATUTORY & REGULATORY COMPLIANCE NOTICE
The statutory references and mortgage guidelines summarized above (including references to the Garn-St. Germain Depository Institutions Act of 1982, 12 U.S.C. § 1701j-3, and Consumer Financial Protection Bureau 12 CFR § 1024.30 Regulation X) are provided strictly for educational and mortgage planning orientation. Dianna Michele Thompson provides residential mortgage origination and structured estate financing consultation; she is not an attorney, estate planning legal counsel, or certified public accountant. Nothing contained on this site constitutes formal legal counsel, judicial probate advice, or individual tax representation. Estate administrators, trustees, and successors must consult their independent probate counsel and licensed tax advisor regarding jurisdiction-specific probate rules, fiduciary duties, and tax consequences before executing property transfers or loan restructuring.
ESTATE PLANNING & REAL ESTATE FINANCING
Navigate Real Estate Decisions With
Confidence
Let's help clients navigate real estate and mortgage decisions with confidence.
Direct Professional & Attorney Collaboration · Strategic Mortgage Alignment · Fiduciary Integrity