MORTGAGE SOLUTIONS
Self-Employed?
Your Path to Homeownership Starts Here.
Traditional underwriting rarely fits entrepreneurship. Depending on your revenue streams, credit profile, and business assets, there are clear, structured financing paths designed to qualify self-employed borrowers without unnecessary friction.
1099 & Bank Statement Solutions · Licensed Advisory
QUALIFYING PROFILES
Who Is Considered
Self-Employed?
Lenders evaluate independent earning structures differently than standard W-2 wages. If you drive your own income, your financial profile fits one of these primary categories.
Small Business Owners
Founders and majority stakeholders managing an LLC, S-Corp, or C-Corp entity with operational revenues and business balance sheets.
Freelancers & Contractors
Independent service providers, consultants, creatives, and technical specialists executing retained or project-based client agreements.
1099 Income Earners
Professionals receiving gross non-employee compensation without payroll withholdings, such as real estate agents, gig specialists, and sales reps.
Sole Proprietors & Partners
Unincorporated single operators reporting on Schedule C, as well as formal partners filing Form 1065 / K-1 distributions.
UNDERWRITING METHODOLOGY
How Lenders See
Your Income
While your certified public accountant structures your filings to minimize taxable profit, residential mortgage underwriters look through an entirely different lens: verifying consistent, sustainable net cash flow available for personal debt service.
ANALYSIS PHASE 01
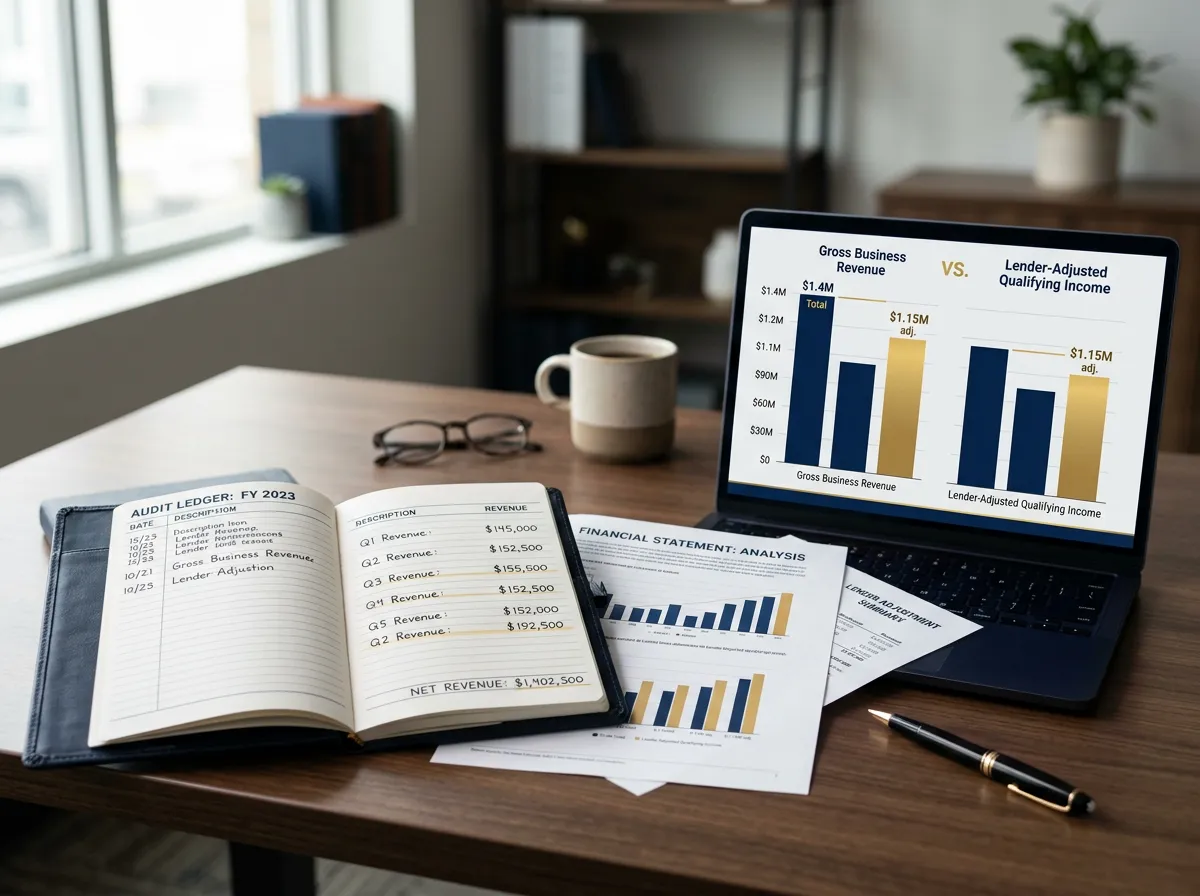
Gross Revenue vs. Net Qualifying Income
An enterprise collecting $1,200,000 in top-line commercial turnover might report $95,000 in adjusted gross income after legitimate corporate write-offs. For conventional underwriting, purchasing power is derived strictly from net taxable figures rather than bank deposit volumes.
- Business entity distributions must prove ongoing corporate liquidity without impairing operations
- Personal tax returns and corporate filings are tied together to prevent double-counting obligations
- W-2 compensation paid to you by your own entity must be validated against business health
ANALYSIS PHASE 02
Stability, Deductions & Debt Isolation
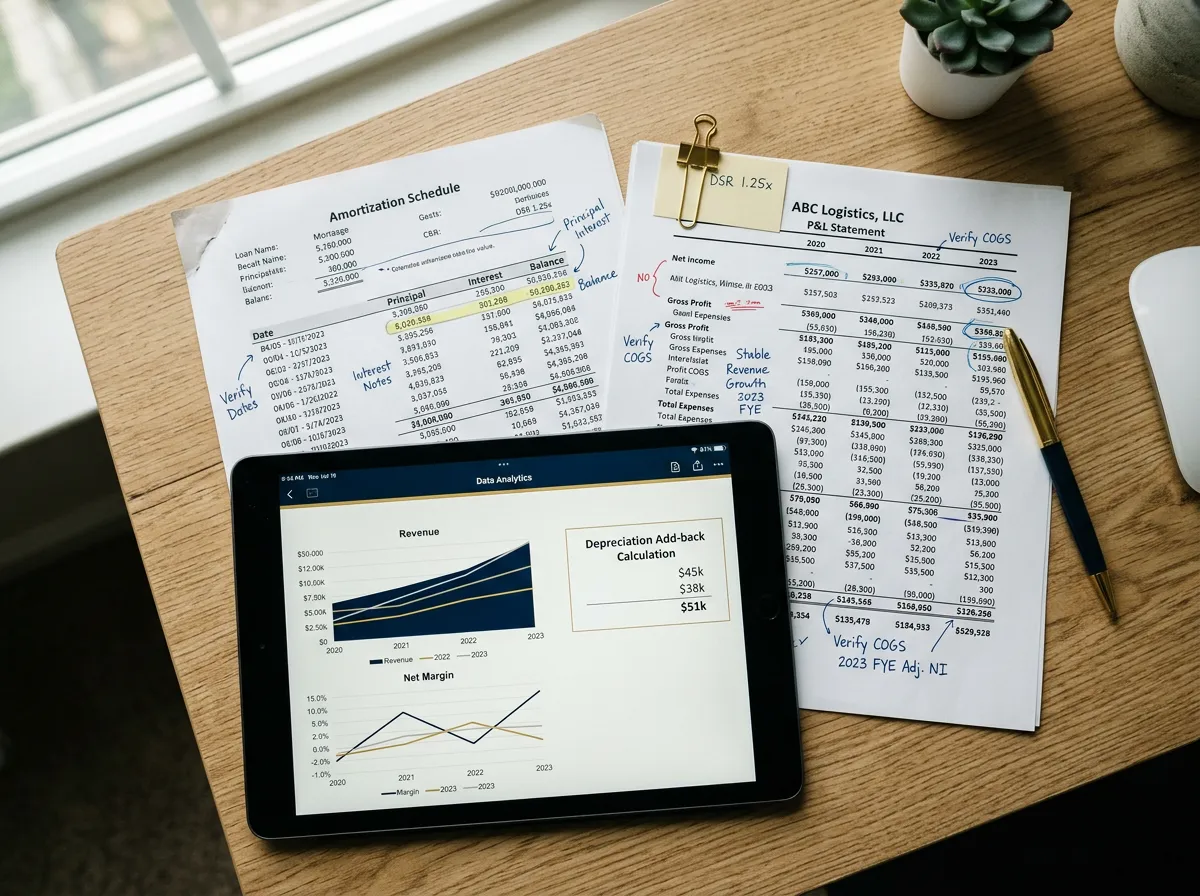
Not every deduction diminishes borrowing strength. Experienced mortgage originators systematically add back non-cash paper losses to restore qualifying income. Simultaneously, multi-year revenue trends determine whether the underwriter applies a two-year average or strictly the lower, most recent period.
- Non-cash expenses such as depreciation and asset amortization are credited back to income
- Two-year stability trends protect against temporary market dips if baseline viability remains solid
- Commercial debts paid from entity accounts for 12+ months are excluded from personal liabilities
FINANCING PORTFOLIO
Mortgage Options for
Business Owners
Whether you optimize for maximum tax deductions or prefer traditional agency guidelines, we match your operational structure with the optimal lending framework.
AGENCY & CONFORMING
Conventional & FHA
Rigorous traditional lending suited for established business entities reporting healthy, consistent net taxable income.
- 2 years verified business and personal tax returns
- Down payments starting from 3% to 3.5%
- Fannie Mae / Freddie Mac underwriting parity
- Heavy tax write-offs directly reduce borrowing capacity
GOVERNMENT-BACKED
VA & USDA Programs
Targeted federal initiatives designed to provide zero-down capital solutions for eligible military veterans and rural enterprises.
- 0% down payment financing options available
- Competitive government-backed fixed interest rates
- Strict geographic or military service eligibility
- Standard 2-year self-employed tax filing documentation
ALTERNATIVE NON-QM
Bank Statement Loans
Premier solution for entrepreneurs whose actual cash flow far exceeds reported taxable net income due to legal tax deductions.
- Qualified via 12 to 24 months of verified revenue deposits
- Zero personal or business tax returns required
- Preserves full legal deductions and operational write-offs
- Down payment minimums typically range from 10% to 20%
Regulatory Disclosure: All mortgage loan programs are subject to formal underwriting review, credit qualification, asset verification, and acceptable collateral appraisal. Financing terms and interest rates are determined by borrower profile and subject to change without prior notice. Loan approval is not guaranteed. Equal Housing Opportunity.
PREPARATION ROADMAP
Your Document
Dossier
Gathering mortgage documentation as an entrepreneur can feel tedious, but clarity starts with having the right records ready in advance. An organized portfolio eliminates weeks of back-and-forth underwriting questions.
Underwriter Rule of Thumb: Lenders evaluate steady cash flow, personal liquidity, and ownership percentage. Having clear electronic copies ready expedites review by up to 60%.
Required Documentation Checklist
Form 1040s, 1120-S, or 1065s including all federal schedules, W-2s, and K-1s showing corporate ownership share.
Interim balance sheet and P&L statement verified by your CPA or bookkeeper, reflecting current operating health.
Consecutive monthly statements for business and personal accounts demonstrating stable liquidity and transaction volume.
Valid government-issued ID, articles of incorporation, business license, or active state registry verification.
REALISTIC SOLUTIONS FOR ENTREPRENEURS
Navigating Common
Challenges
Traditional underwriting algorithms are calibrated for predictable W-2 paystubs. For business owners, disciplined tax planning and cyclical cash flows often trigger automated skepticism. We break down the real underwriting logic behind each hurdle so you know exactly where you stand before applying.
Confidential, one-on-one scenario analysis without credit impact.
CHALLENGE 01 : TAX PLANNING FRICTION
Heavy Tax Deductions
Strategic business write-offs protect your working capital, but standard agency underwriting treats your adjusted gross income as your total buying power. In professional analysis, qualified non-cash expenses such as depreciation, amortization, and vehicle write-offs can often be added back into qualifying income. Alternatively, 12-to-24-month bank statement programs allow qualification based on top-line business deposits rather than declared taxable profit.
CHALLENGE 02 : REVENUE CYCLICALITY
Fluctuating Income
Entrepreneurs and consultants frequently experience quarterly peaks and quieter seasonal periods. Automated underwriting engines often penalize any year-over-year dip. By preparing a multi-year trend analysis, documenting capital reserves, and showing steady average earnings over a 24-month horizon, we can establish financial stability and counter rigid automated assumptions.
CHALLENGE 03 : OPERATIONAL VINTAGE
Recently Established Businesses
Most conforming lenders require an unyielding two full years of filed tax history for new enterprises. However, if you have between 12 and 23 months of self-employment history with verifiable prior W-2 leadership in the identical trade, specialized loan products and portfolio guidelines can bridge the timeline requirement without waiting for another filing season.
Specialized Underwriting Guidance
Your Trusted
Advocate
Navigating mortgage approval as an entrepreneur or independent professional requires more than automated checklists. Dianna Michele Thompson specializes in translating non-traditional revenue streams and complex write-offs into clear, lender-ready financing packages.
With deep command over bank statement programs, asset utilization formulas, and 1099 structures, Dianna provides hands-on strategic advisory from pre-approval through funding. Every client receives dedicated guidance, proactive communication, and customized positioning tailored to their specific financial footprint.
VERIFIED MORTGAGE EXPERTLICENSED ORIGINATOR • SPECIALIZED SELF-EMPLOYED LENDING
Direct consultation with Dianna • Confidential file analysis • Zero obligation
CLARITY
Answers for
Entrepreneurs
Self-employed underwriting is governed by strict agency and portfolio benchmarks. Here are the factual guidelines behind 1099 verification, tax return add-backs, and alternate cash-flow financing.
Can I qualify for a conventional loan with only one year of 1099 self-employment?
Yes, under specific agency underwriting rules. While standard Fannie Mae Selling Guide (B3-3.2-01) mandates a consecutive two-year track record, Desktop Underwriter (DU) can grant an exception for 12 to 24 months of verified 1099 income if you demonstrate continuous prior employment in the identical line of work with documented earning stability.
How do bank statement loan programs calculate qualifying income without tax returns?
Non-QM bank statement underwriting calculates income by aggregating total deposits across 12 or 24 consecutive months from either business or personal accounts. For business accounts, a standardized expense factor (typically 50%, or a custom ratio certified by your CPA via letter) is deducted to establish qualifying net monthly cash flow.
Do aggressive business tax deductions reduce my mortgage borrowing capacity?
On agency conforming (Fannie Mae, Freddie Mac) and FHA loans, qualifying income is rooted in taxable net income, meaning heavy write-offs reduce buying power. However, non-cash paper losses such as depreciation, Section 179 property deductions, and amortization are added back to your gross income during the Fannie Mae Form 1084 calculation.
Can I combine concurrent W-2 earnings with my 1099 contract revenue?
Yes. Borrowers with simultaneous W-2 employment and freelance or 1099 consulting revenue can utilize both income streams. Per HUD Single Family Housing Policy Handbook 4000.1, the secondary 1099 revenue must have a documented 2-year uninterrupted history to demonstrate that holding dual roles does not compromise earning stability.
When is the optimal time to consult a mortgage specialist relative to filing taxes?
The ideal timing is at least 60 to 90 days before completing and submitting your annual tax returns to the IRS. Reviewing draft Schedule C or corporate 1120-S filings allows you to balance necessary tax write-offs with the explicit debt-to-income benchmarks required for your target home acquisition.
DIRECT ADVISORY PARTNERSHIP
Your Business Is Different.
Your Mortgage Options May Be, Too.
You have built an enterprise that defies standard underwriting formulas. Partner directly with an experienced lending specialist to design a financing structure aligned with your true tax profile, business liquidity, and long-term wealth goals.
Direct Consultation • Confidential Review of Business Returns • Flexible Loan Programs